
UK warned over ballooning debt costs and slower growth ahead of Budget
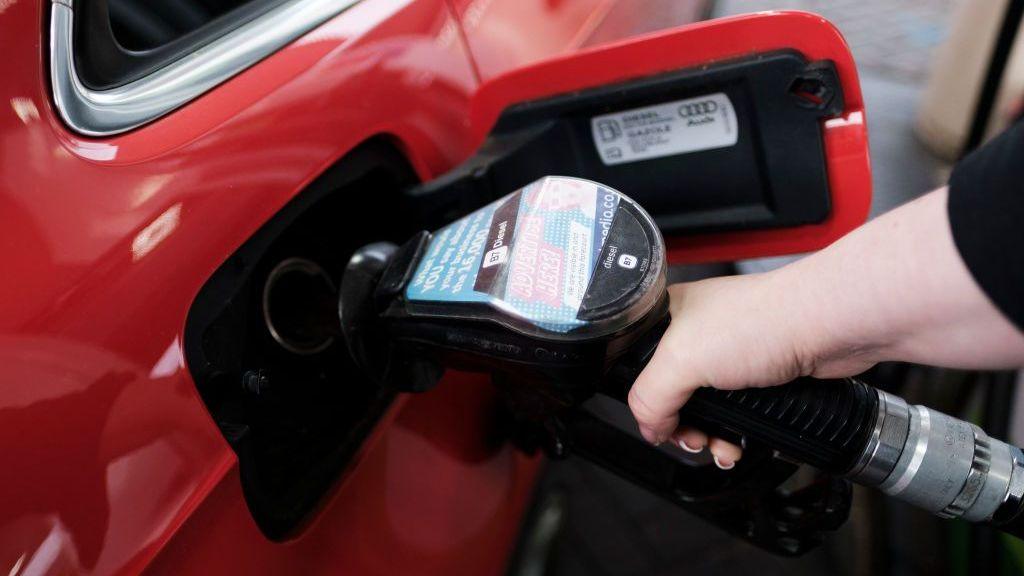 Image source, Getty Images
-
Published
The UK has been warned over ballooning debt costs and slower economic growth ahead of Chancellor John Healey’s first Budget next month.
The UK was among countries facing downgraded growth forecasts in a report by the influential Organisation of Economic Co-operation and Development (OECD) on Wednesday.
That came as the head of the International Monetary Fund (IMF) told the BBC that Britain and the US needed to reduce debt due to spiralling borrowing costs.
The ongoing conflict in the Middle East and the Russia-Ukraine war has pushed up the cost of crude oil leading to higher fuel and energy costs, which in turn has driven up inflation around the world.
The UK economy will grow by slightly less than expected next year, according to the OECD which now expects growth of 1% next year rather than 1.1%.
However, it said the UK had proved more resilient than expected this year, upgrading its forecast for growth 0.9% to 1.1%.
Meanwhile, IMF head Kristalina Georgieva told the BBC on Tuesday that global economic shocks had been “pushing debt levels up like a staircase not to heaven” but that governments had taken “no action to contain that service cost”.
“[It’s] time to take that action,” she said, adding that “courage” was needed by politicians to take the necessary steps.
To play this video you need to enable JavaScript in your browser.
This video can not be played
Inflation has also pushed up the cost of interest on government debt, which alongside an unexpected surge in government borrowing in August has added to the pressure on Healey.
Prime Minister Andy Burnham has made easing the cost of living for households one of his key aims, while the government is under pressure to spend more on defence.
However, Burnham and Healey face a difficult balancing act, trying to offer more support to households while sticking to Labour’s manifesto commitments on tax and the government’s self-imposed fiscal rules.
The impact of higher fuel prices next year depends on how long supply disruptions last, the OECD said. Stockpiles of oil and supplies from outside the Gulf states have helped cushion the effects on economies so far, it said.
Risks to the global economy include the war in the Middle East and climate-change related supply shocks, the OECD said.
Next year, global growth is expected to also be 0.1% lower, with countries affected including Australia, Canada, and the Euro-area.
Conflict in the Middle East has contributed to higher oil and gas prices globally, pushing up inflation in countries including the UK.
Weather-related shocks, including from a strong El Nino, could hit farmers and help push up food prices, it added.
In addition, tariffs and export restrictions on trade continue to add to uncertainty, it said. New US tariffs from July as part of the Trump administration’s ongoing volatile trade policy have raised its effective tariff rate by 1%.
Chief Secretary to the Treasury Emma Reynolds said: “Despite unprecedented pressures and conflict in both the Middle East and in Europe, the UK economy is showing strong resilience.”
She added that the government is “already giving families space to breathe” and “starting the big, long-term changes needed to create good jobs and growth in every postcode”.
However, Conservative shadow chancellor Andrew Griffith said the OECD urges countries to “control spending and improve public sector efficiency”.
“Instead, this government is trying to find new ways to tax you whilst having to pay interest rates on their borrowing which are the highest in the G7,” he said.