
That simple transaction reveals an important feature of the broadband industry: the company selling the connection often does not own the network delivering it.
Behind the monthly bill sit two distinct businesses. One builds and maintains infrastructure, investing capital that may take years to recover.
The other sells services over that infrastructure, competing for customers through pricing, branding and support. Their economics help explain why similar-looking packages can carry different prices, and why owning a fibre network does not guarantee a profitable business.
One network, competing brands
In Britain, Openreach supplies network services to communications providers, which then sell broadband packages to households and businesses. Openreach remains part of BT Group, but its wholesale customers include competing providers. It says it supplies products on equal terms regardless of who buys them.
This structure allows retail competition without requiring every broadband brand to dig up the same street.
However, sharing an access network does not make providers interchangeable. Beyond the connection to the premises, providers can differ in network capacity, traffic routing, equipment, customer support and contractual commitments.
Those choices affect both the customer experience and the provider’s costs. A company investing heavily in support operates differently from one prioritising low prices and automated service, even when both use the same underlying fibre network.
For customers, the brand on the bill describes only part of the supply chain. For investors, it identifies a business whose returns depend heavily on how efficiently it acquires and retains subscribers.
The gap between price and profit
A retail provider’s margin starts with subscription revenue, excluding applicable taxes, less the cost of supplying the service. Wholesale network access is a major expense, but it is far from the only one.
The provider must also fund connectivity beyond the access network, routers, billing systems, support and customer acquisition. Some buy a more complete wholesale service through an intermediary; others operate more of their own network.
An illustrative calculation shows how quickly the apparent margin can narrow. Suppose a provider earns £30 a month excluding VAT and pays £18 for wholesale access. The remaining £12 is not net profit. Other service costs and overheads still need to be covered.
If acquiring that subscriber costs £120 and the provider earns £5 a month in contribution after ongoing service costs, recovering the acquisition expenditure takes 24 months.
A customer leaving earlier can undermine the economics. These figures are hypothetical, but the relationship explains why retention matters as much as sign-ups.
Discounts, cashback and introductory offers therefore represent investments in future customer revenue. Their success depends on how long subscribers stay and what it costs to serve them.
A low headline price can attract customers, but it reveals little about the sustainability of the business supplying the connection.
Owning the network changes the calculation
Alternative network operators, or altnets, introduce another business model. Some combine infrastructure ownership with retail sales. Others sell wholesale access to competing providers.
CityFibre, for example, operates a wholesale-only model, supplying its network to ISP partners rather than selling household broadband subscriptions directly.
A business that owns its network and sells directly can retain revenue that would otherwise go to a separate access-network supplier. But it also assumes the construction, maintenance and financing obligations behind that infrastructure.
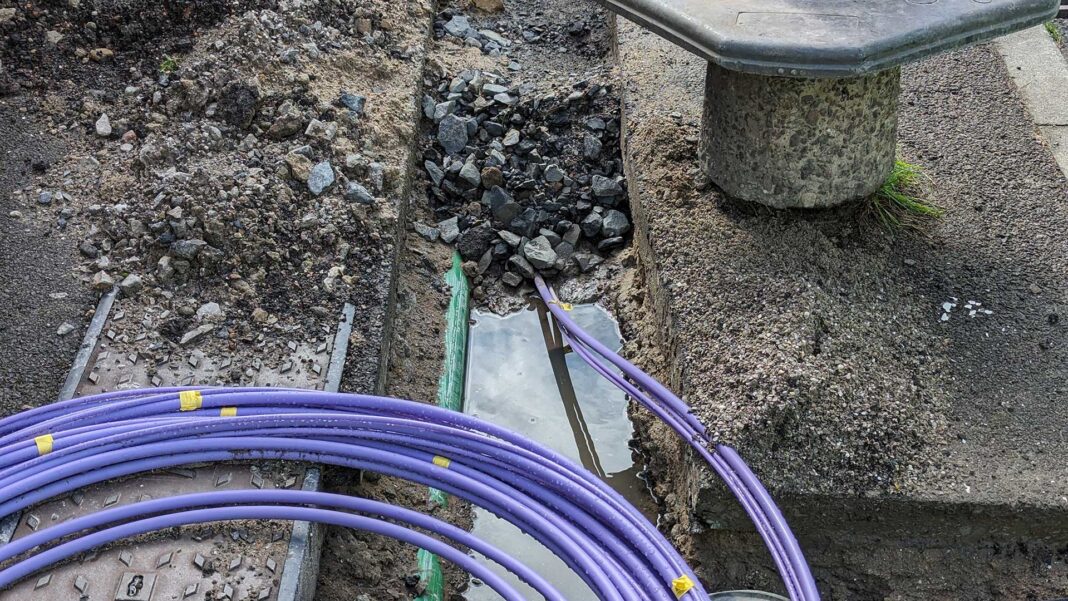
Civil engineering, equipment and installation require substantial expenditure before subscription income arrives. Once built, the network needs enough paying connections to support those costs. A street full of fibre-ready properties offers commercial potential; it does not necessarily deliver revenue.
CityFibre’s February 2025 trading update illustrates the distinction. For 2024, it reported £134 million in revenue and £5 million in adjusted EBITDA, approximately a 3.7% margin on that measure.
Its network had passed more than 4.3 million premises, while live customers numbered 518,000. These historical figures show why customer take-up matters alongside construction progress.
Adjusted EBITDA excludes interest, tax, depreciation and amortisation. A positive result on that measure does not establish that construction investment has been recovered or that shareholders are receiving a net profit.
As networks mature, adding customers to existing infrastructure can improve operating economics. The challenge is funding the business long enough to reach that position.
New Zealand offers a parallel
New Zealand makes the distinction between infrastructure and retail particularly clear. Its Ultra-Fast Broadband initiative was delivered through four principal fibre wholesalers: Chorus, Enable, Northpower and Tuatahi. The networks were established on a wholesale-only basis, with retail service providers selling connections to end users.
The commercial division resembles Britain’s Openreach-based model, although the ownership and regulatory arrangements differ.
Customers choose a provider, while the local fibre network can remain the same when they switch. Retailers compete over a shared infrastructure platform rather than each constructing a separate connection to every household.
“The New Zealand model makes the distinction easier to understand,” says Tomas Novosad, founder of Fibre Broadband NZ. “Choosing a fibre provider often means choosing who packages, supports and bills the service over an existing network. The retailer’s job is to make that relationship commercially viable.”
Infrastructure returns are also subject to regulatory scrutiny. New Zealand’s Commerce Commission applies information disclosure requirements to the four regulated fibre wholesalers, with Chorus additionally subject to price-quality regulation. This allows the regulator to set maximum revenue and minimum quality standards for Chorus’ regulated services.
The return depends on the business model
There is no single broadband profit margin. A retailer’s returns depend on wholesale purchasing, acquisition costs, service delivery and retention. A network owner’s returns depend on construction costs, utilisation, financing and the time required to earn back its investment.
Even apparently straightforward revenue comparisons require care. BT reported Openreach broadband average revenue per user of £16.70 for its financial year ended March 2026. That is a reported average across its broadband base, rather than a universal wholesale tariff or a measure of profit per connection.
For business buyers, understanding these layers makes broadband procurement more informed. A higher price may fund better support or stronger service commitments, but the price alone does not demonstrate either.
For broadband companies, the central challenge is converting recurring subscriptions into durable returns. Retailers need customers who stay long enough to justify acquiring them. Infrastructure owners need those subscriptions flowing across networks built at considerable upfront cost. Both depend on what happens long after the introductory deal ends.