
Why we bought our first home with a 100% mortgage – despite the risks
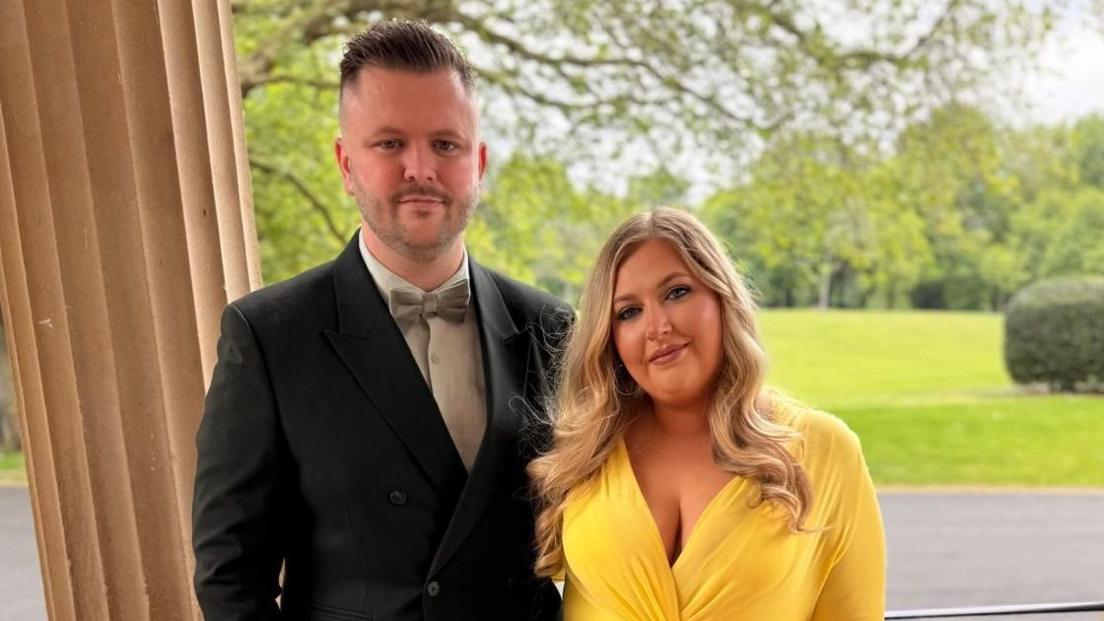 Image source, Supplied
-
Published
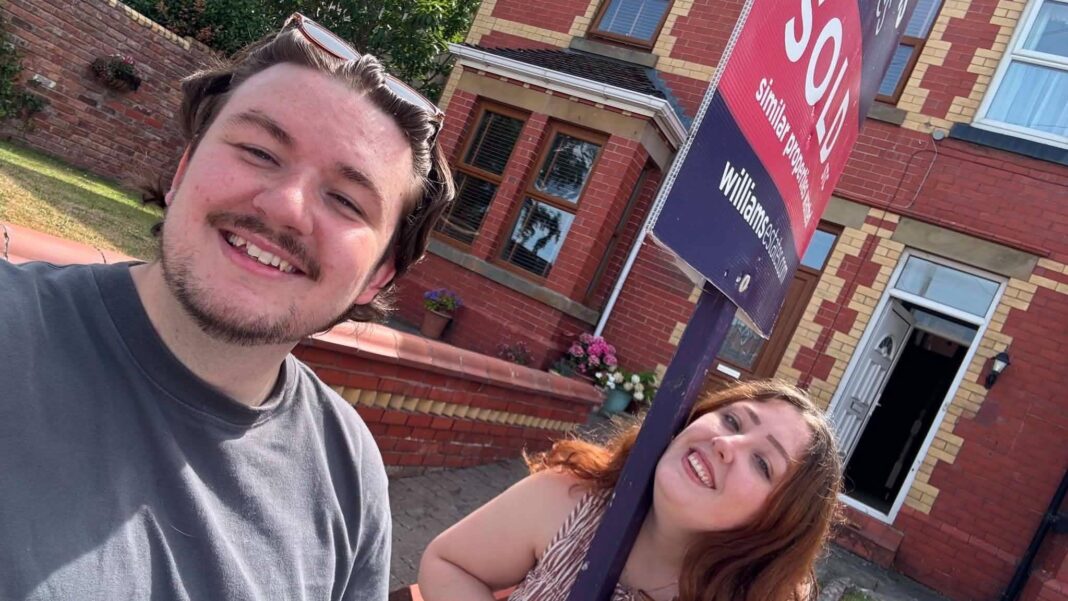
Until last year, Conroy, 32, and his partner Amber, 28, saw little prospect of owning their own home. They were renting in central Manchester where they work and could not afford to save up for a deposit.
Then they came across a relatively niche, and some experts say riskier, type of mortgage that offered a solution.
The Track Record mortgage from Skipton Building Society covers 100% of the value of a property, with the borrower paying nothing upfront.
Borrowers must meet strict eligibility checks and pay a higher interest rate – in Conroy and Amber’s case 5.33% fixed for five years – but they were happy to do this. And in August they bought a four-bed home for £242,000 in Swinton on the edge of Manchester.
“I don’t think it’s dawned on us it’s really ours,” says Conroy, a video editor.
The return of low-deposit deals
According to the Bank of England, the share of UK mortgages with deposits worth less than 10% of the property’s value is currently the highest it has been since 2008, external when such loans were widely available.
The average deposit for first-time buyers is currently around 20%.
It comes as lenders such as Lloyds, Santander, Skipton and Yorkshire Building Society have launched a raft of new mortgage deals over the last few years covering upwards of 95% of the value of a property, and in some cases as much as 100%.
They say they want to help first-time buyers get on the housing ladder as property prices continue to rise and while saving for a deposit remains a struggle.
But these loans tend to charge higher rates, aren’t available for all types of property or borrower, and come with risks customers should be aware of.
 Image source, Conroy & Amber
Conroy and Amber, a solicitor, have a 25-year loan with monthly repayments of £1,500 – roughly what they were paying in rent.
He says they feel comfortable with the higher cost because they “earn quite well” and expect their salaries to rise.
But he is aware there is a greater risk of falling into negative equity with a no- or low-deposit mortgage. That is when the value of a property falls below the value of the loan still owed on it – leaving the borrower with potentially painful costs if they suddenly have to sell.
Conroy says they plan to overpay their mortgage for the first five years to build up more equity in their home.
“There is always the element of a gamble with the property market,” he says.
“But I have researched the area we moved to and don’t think house prices are going to drop.”
‘We plan to stay here our whole lives’
Twenty-seven-year-old Bronya and her partner George, 29, also used a low-deposit mortgage to buy their four-bedroom house in Rhuddlan, North Wales in August.
Lloyds lent them £258,000 – roughly 98% of the property’s value – over a 33-year term and they only had to put down £5,000 as a deposit.
The couple pay an interest rate of 5.89%, fixed for five years, equating to monthly repayments of £1,400 – about the same as what they paid to rent a one-bed flat before.
Bronya, a civil servant, says they could have put down a bigger deposit but wanted to use their savings for a renovation project costing upwards of £20,000.
They are aware of the risks of negative equity but believe the refurbishment will boost the value of their home.
“We also plan to stay here our whole lives,” George adds, explaining that they are prepared to ride out any dips in the property market.
 Image source, Supplied
Widespread uptake of low-deposit mortgages by borrowers who could not afford them was seen as a major factor in the 2008 global financial crisis.
But today’s deals have much stronger affordability checks and do not pose the same risks, says David Hollingworth, associate director at brokers L&C Mortgages.
Borrowers of Skipton’s zero-deposit mortgage, for example, have to prove they have kept up with their rent for at least 12 consecutive months and credit payments for the last six months.
And Lloyds won’t issue one of its £5,000 deposit mortgages for new-build properties and shared ownership homes.
Hollingworth says lenders are recognising that some people have “good affordability but may be struggling to save for a deposit while paying a rent and dealing with cost of living pressures”.
Following a recent rule change, he adds, lenders are also offering more “flex” on how much someone can borrow as long as it’s within their means.
Nevertheless, he urges borrowers to use common sense.
“Think carefully – what do monthly payments look like? Are you aware that interest rates could go up?”
Get in touch
Are you buying your first home? How have you managed it?