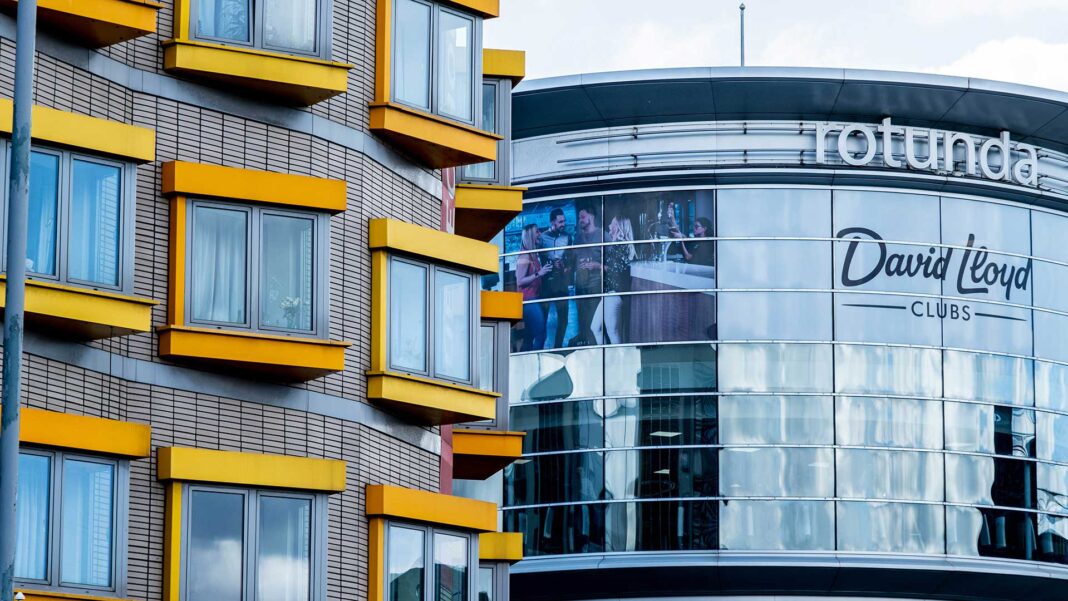

David Lloyd Clubs lost 267,450 members in 2025, equivalent to 34.1 per cent of the members it started the year with, according to the annual accounts of its holding company, Deuce Midco.
The premium health club operator still finished the year with a record 822,000 members, a net gain of 37,000, as new joiners outnumbered leavers. The figures are set out in the Deuce Midco annual report and accounts for 2025, which the board approved on 24 April.
The company measures attrition as the number of members leaving over 12 months divided by the opening membership base. Its 2025 rate improved by 0.7 percentage points on the prior year but missed the 33 per cent target it had set for the year.
The attrition figure was highlighted by Matthew Jenkins in his Three Exits newsletter, published on LinkedIn. Jenkins calculated that David Lloyd had to sign around 300,000 new members during the year, more than 800 a day, to achieve its net growth. On his figures, almost nine in every 10 new sign-ups replaced a member who had left.
The accounts state that retention improves with tenure, and that members who stay beyond 18 months remain for about seven years on average.
Revenue rose 13 per cent to £971.5m in 2025 from £860.8m, and adjusted EBITDA rose 21.8 per cent to £280.9m, according to the accounts. Average monthly yield per member rose 7.7 per cent to £80.88, which the company attributed to demand for its Platinum and Diamond packages and an average price increase of 4.5 per cent.
Members made 62.3 million club visits during the year, and the group reported a Net Promoter Score of +44. It expanded from 66 padel courts to 253 and had Spa Retreats at 52 clubs by 31 December. The expansion forms part of a £500m investment programme that Business Matters reported on in January 2025.
The group paid a £330m dividend in 2025 to its immediate parent, Deuce Parentco, according to the accounts. That company in turn paid a dividend to Deuce Holdco, which used the money to repay in full a payment in kind loan facility, including accrued interest.
The cash flow statement shows £1,293.7m of new borrowing and £910.8m of repayments during the year. On 20 November 2025, subsidiary Deuce FinCo issued £825m and €530m of senior secured notes, due in November 2031 and November 2032 respectively. The sterling notes carry a fixed rate of 7 per cent.
Jenkins calculated that interest on the sterling bonds alone would come to about £58m a year, more than the group paid in interest in 2025. The accounts record interest payments of £51.4m for the year. Net debt excluding lease liabilities rose to £1.24bn from £892m.
Jenkins wrote that the dividend was funded by lenders rather than by the year’s trading, estimating that cash from the clubs fell about £25m short of covering maintenance, new clubs and refurbishments before any payment to shareholders. He described the business as “a club its members love, financed the way a property company is financed.” The group also raised £95m from three sale and leaseback deals covering five clubs, the accounts show.
TDR Capital, which bought David Lloyd in 2013 for £750m, closed a continuation vehicle on 6 November 2025 that acquired majority control of the group from an older TDR fund, according to the accounts. TDR Capital Titan now holds 90.27 per cent of the group’s ultimate parent.
Jenkins noted that TDR had tried to sell the business in 2017 and 2023 without a buyer meeting its price, and that reports valued the continuation deal at about £2bn. Reports in June said TDR was considering a London stock market listing at a valuation of around £4bn. Jenkins said no float had followed and that TDR had not commented publicly.
Membership stood at 829,000 at the end of March 2026, the accounts show. Moody’s rated the new notes B2 in October 2025, while Fitch affirmed the group’s B rating.